Build your crypto strategy without code and test it honestly
Live charts, a block-based strategy builder, backtests with realistic costs and a market scanner, for Binance spot and futures markets.
No payment details · Starts with a Pro trial
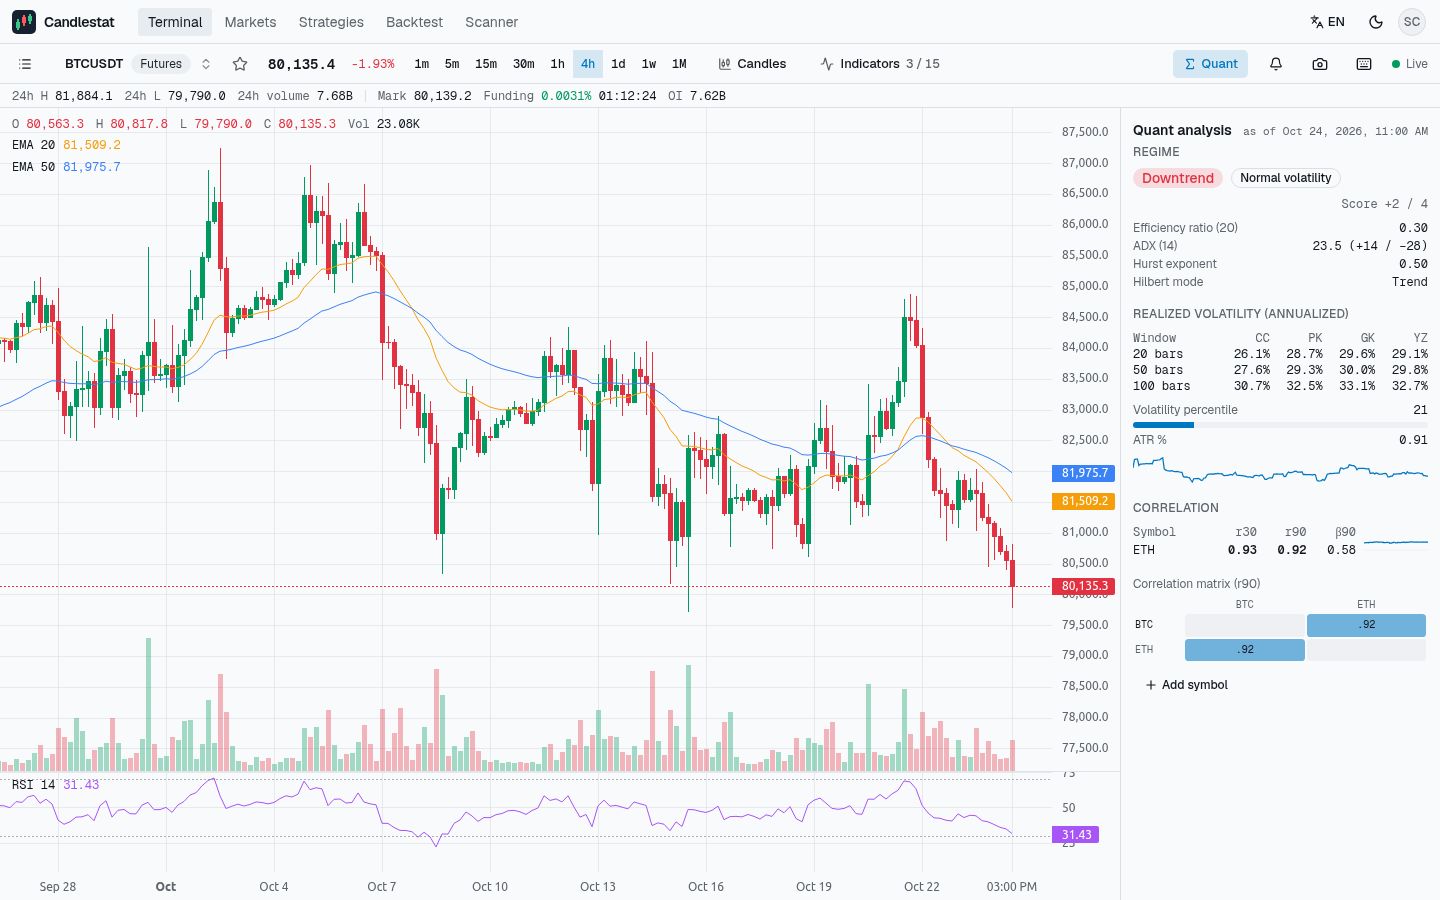
Terminal
Live charts, 45+ indicators, candlestick and SMC patterns, a volatility and correlation panel.
In the guide →Strategy builder
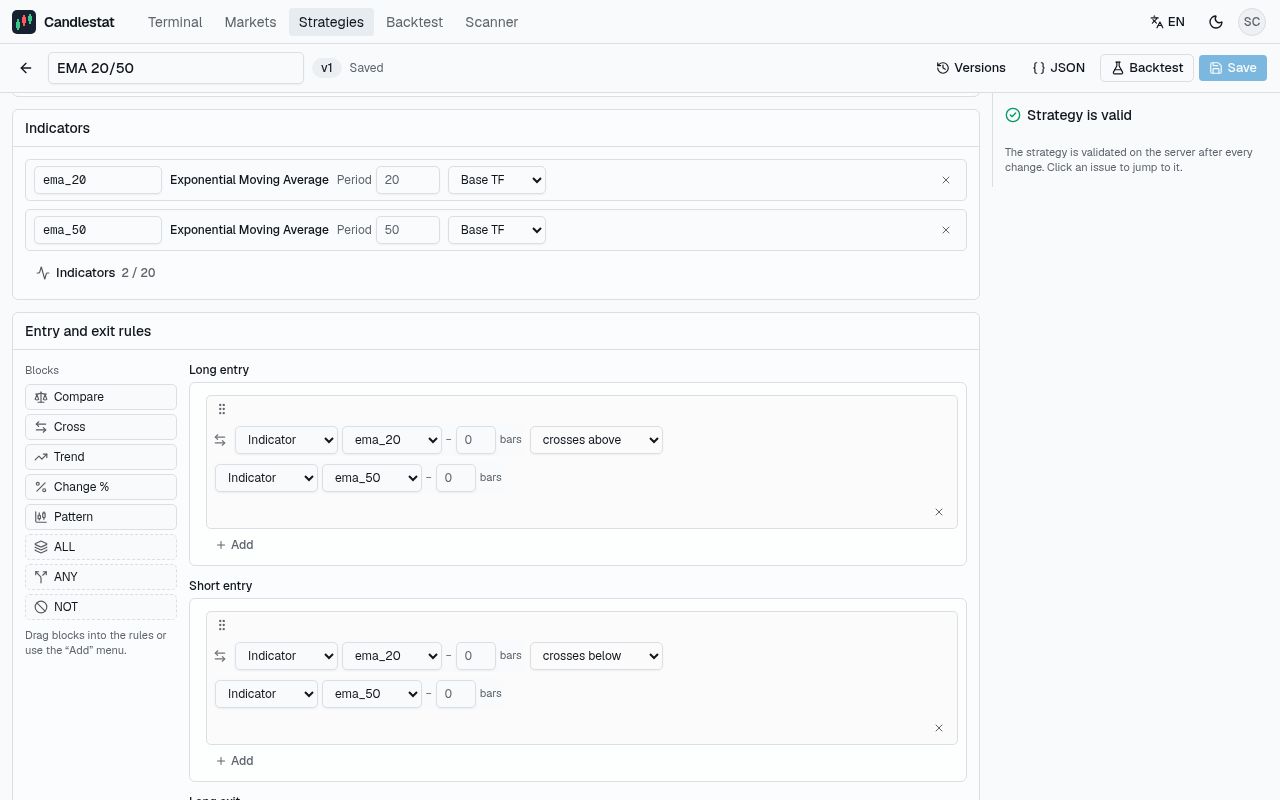
Build entry and exit rules with nested blocks; set risk and position sizing.
In the guide →Backtest and optimization
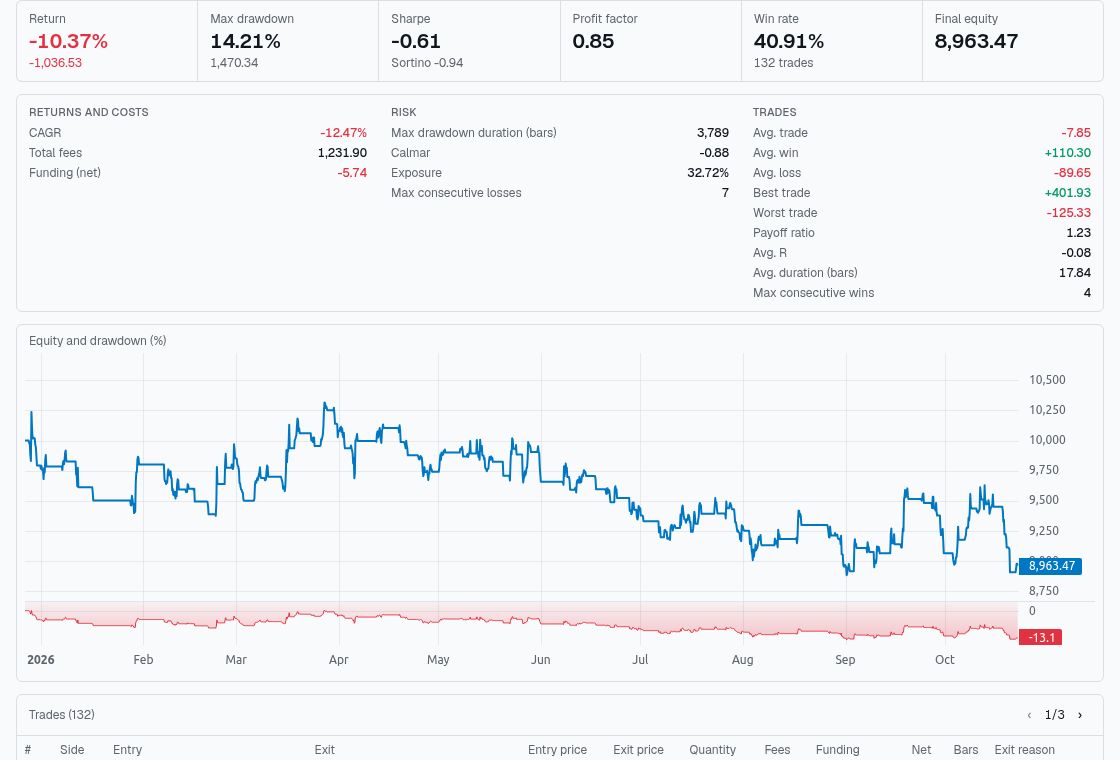
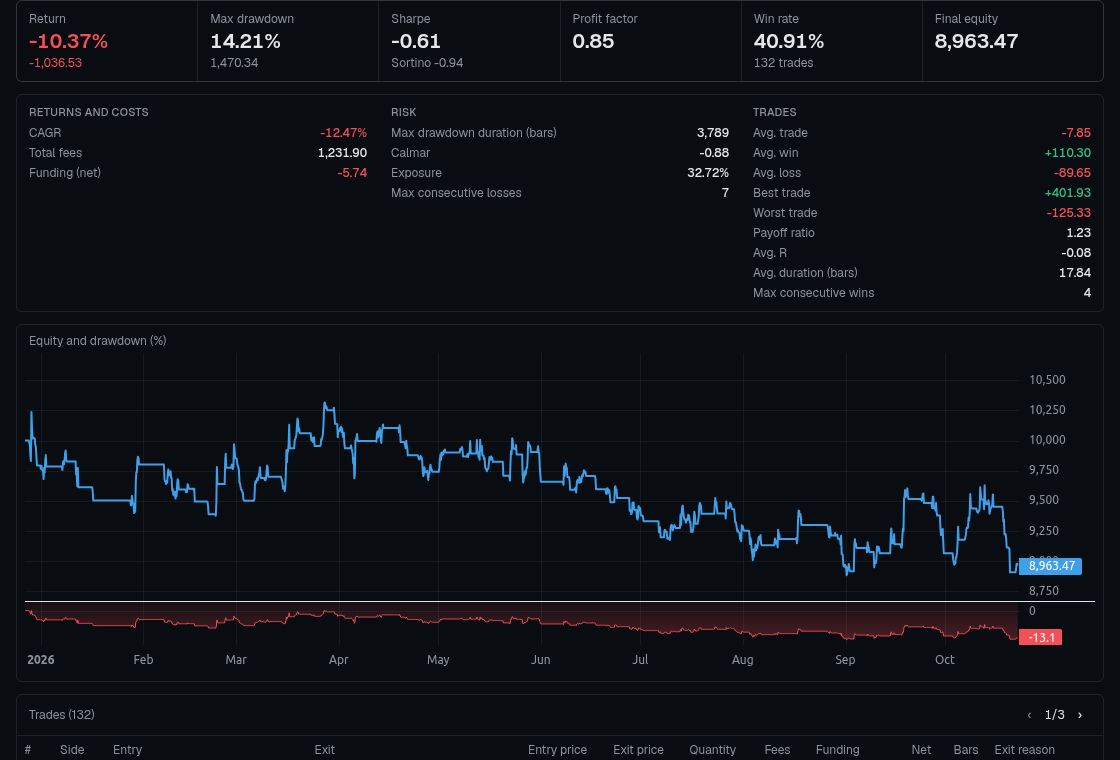
Multi-symbol backtests, detailed metrics and grid optimization with out-of-sample testing.
In the guide →Scanner and alerts
Filter the whole market, run live scans with strategy conditions and set price alerts; get notified in the app, by email and on Telegram.
Strategy builder
Build your rules with nested blocks, without code. The editor validates every change; you can start from ready-made templates.
- Compare, cross, trend, change and pattern blocks; AND/OR/NOT
- Stop-loss, take-profit, trailing stop and R-based risk
- Every save is an immutable version: backtest results are reproducible
Backtest and optimization
Run your strategy on historical data across several symbols; inspect trades, the equity curve and metrics. Sweep parameters and test the best ones on data they have not seen.
- Conservative fills with fees, slippage and a bar-volume limit
- Sharpe, Sortino, Calmar, max drawdown, profit factor, average R
- Optimization trains on 70%, then tests the best 10 combinations on the last 30%
So results don't look better than they are
A backtest that looks great but fails in reality is worse than no backtest at all. That's why:
- Chart and backtest share code
- Indicators are computed by the same functions on the chart, in strategies and in backtests.
- No lookahead
- Rules are evaluated at the bar close and orders fill at the next open; higher timeframes only expose closed bars.
- Conservative costs
- Fees, slippage and a volume limit are on by default; if stop and target hit on the same bar, the stop comes first.
- Out-of-sample testing
- The best optimization results are tested again on a period they have never seen, so overfitting becomes visible.
- Measured for crypto
- Annualization is 24/7; the stock-market assumption of 252 trading days is not used.
- Reproducible
- Every backtest is tied to a specific strategy version; the same settings always give the same result.
Paper Trading
Run your strategy on the live market with a virtual balance, using the same order logic as the backtest.
Test your first strategy today
Creating an account is free; every new account starts with a Pro trial.